Ally Bank Review 2026: Is This the Best Online Bank for Beginners?
Choosing your first bank account can feel more complicated than it should be. Between confusing fee schedules, low interest rates, and branches that never seem to be open when you need them, it’s no wonder so many beginners default to whatever bank their parents used. This Ally Bank Review looks at whether one of the most talked-about online banks actually lives up to its reputation, especially for someone just starting to take their finances seriously.
Ally has been operating as a fully online bank since 2009, and it has built a strong following among people who want competitive interest rates without the monthly fees common at traditional banks. But “popular” doesn’t automatically mean “right for you,” so let’s break down exactly what you get.
What Is Ally Bank?
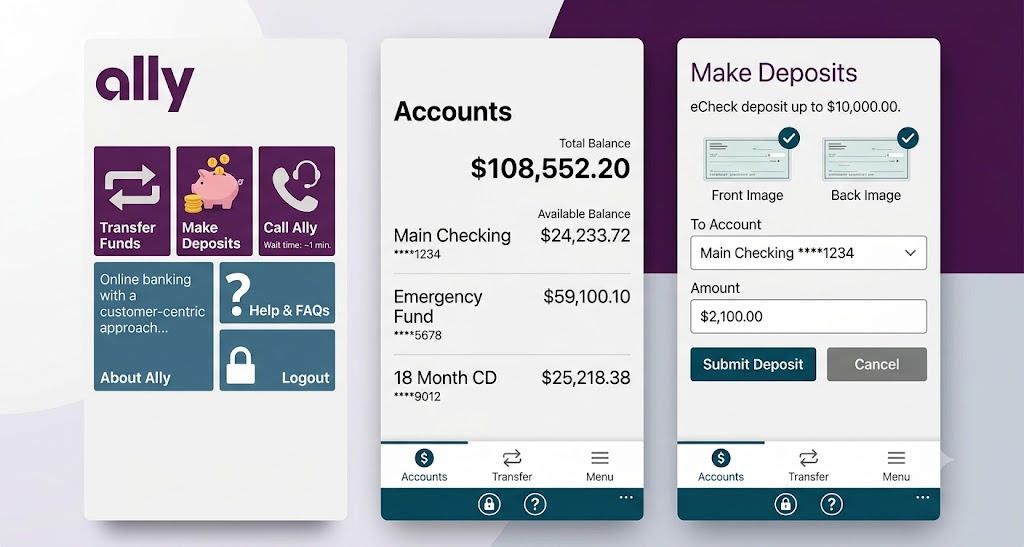
Ally Bank is an online-only financial institution, meaning it has no physical branches. Instead, it operates entirely through its website and mobile app, which allows it to keep overhead low and pass some of those savings on to customers in the form of higher interest rates and fewer fees. It’s FDIC insured through certificate #57803, so deposits are protected up to $250,000 per depositor, per ownership category — the same federal protection you’d get at any traditional bank.
Ally Bank Review: Key Features Every Beginner Should Know
Ally Bank Review: Competitive, Fee-Free Savings Account
The centerpiece of most Ally accounts is its Online Savings Account. As of mid-2026, the account pays a variable APY of roughly 3.00%, well above the national average for savings accounts, which typically hovers below 0.50%. There’s no monthly maintenance fee, no minimum opening deposit, and no minimum balance required to earn interest. Keep in mind the rate is variable, so it will move up or down with broader interest rate trends — always check the current rate before opening an account.
Savings Buckets: A Beginner-Friendly Organization Tool
One of Ally’s standout features is Buckets, a system that lets you divide a single savings account into up to 30 virtual sub-accounts for different goals — think emergency fund, vacation, car repairs, or holiday shopping — without needing to open separate accounts. Every bucket earns the same interest rate, and you can see your progress toward each goal at a glance. For beginners who find spreadsheets overwhelming, this visual approach makes goal-based saving far more approachable.
Automated Savings Tools
Ally also offers “Surprise Savings,” a feature that analyzes your linked checking account activity to identify small amounts you can safely move into savings without risking an overdraft, and automatically transfers them. There’s also a round-up feature that rounds debit card purchases to the nearest dollar and deposits the difference into savings. Combined with recurring transfers, these automation tools make it easier for beginners to build savings habits without having to think about it constantly.
Checking Account and ATM Access
Ally’s interest-bearing checking account has no monthly fees and reimburses up to $10 in out-of-network ATM fees per statement cycle. Customers also get free access to a large network of fee-free ATMs. It’s worth noting that if you only open a savings account without linking a checking account, ATM access for withdrawals becomes more limited, so most beginners will want to open both together.
24/7 Customer Support
Because Ally has no physical branches, it leans heavily on customer service availability to compensate. Live phone support is available 24/7, which is a genuine advantage for anyone who’s ever been stuck waiting for a traditional bank to open during business hours.
Fees and Rates at a Glance
Here’s a quick summary of what to expect:
- Monthly maintenance fees: None
- Minimum opening deposit: $0
- Overdraft fees on checking: None
- Savings APY: Variable, roughly 3.00% as of mid-2026 (confirm current rate before opening)
- CD terms: Range from three months to five years, with no minimum deposit required
- ATM reimbursement: Up to $10 per statement cycle for out-of-network fees
Compared to the fee structures at many traditional brick-and-mortar banks, which can charge $10-$15 a month just to maintain a basic checking account, Ally’s zero-fee approach is a meaningful advantage for beginners who are still building their financial cushion.
Who Should (and Shouldn’t) Use Ally Bank
Based on everything in this Ally Bank Review, Ally is a strong choice if:
- You want a high-yield savings account with no monthly fees or minimum balance requirements.
- You like the idea of organizing your savings visually into goal-based buckets rather than juggling multiple accounts.
- You’re comfortable banking entirely online and don’t need in-person branch access.
- You value responsive customer support outside of normal business hours.
It might not be the right fit if:
- You regularly need to deposit cash, since Ally has no branches and cash deposits require a workaround through a partner network.
- You want the single highest APY on the market — some competitors edge out Ally by a fraction of a percentage point.
- You strongly prefer face-to-face banking relationships.
Pros and Cons Summary
| Pros MD | Cons MD |
| No monthly fees, no minimum deposit, no overdraft fees on checking | No physical branches or easy cash deposit options |
| Competitive, consistently above-average savings APY | Savings rate trails a handful of top-yield competitors by a small margin |
| Savings Buckets make goal-based saving intuitive for beginners | ATM access is more limited without a linked checking account |
| Automated savings tools (Surprise Savings, round-ups, recurring transfers) | Rate is variable and can decrease when broader interest rates fall |
| 24/7 live customer support | |
| FDIC insured up to $250,000 per depositor |
Final Verdict
For beginners looking to open their first serious savings account, this Ally Bank Review lands firmly on the positive side. The combination of a competitive interest rate, zero fees, and beginner-friendly tools like Savings Buckets makes it easy to start building good financial habits without worrying about hidden costs eating into your progress. It won’t be the single highest-paying account on the market at every moment, but the overall package — rate, tools, and support — is hard to beat for someone just getting started.
If you’re comparing your first online bank options, Ally is a safe, well-established place to open both a savings and checking account, especially if you plan to pair it with a dedicated budgeting app to manage day-to-day spending on top of your savings goals.